This section highlights revisions related to:
- defining substantive analytical procedures;
- results of analytical procedures performed as risk assessment procedures; and
- designing and performing substantive analytical procedures.
The section presents key proposed changes, explains why the changes matter, and where relevant, identifies key scalability considerations. Relevant references to the IAASB’s Exposure Draft are also provided.
Defining substantive analytical procedures (SAPs)
Key proposed changes
- Proposed definition of SAPs in paragraph IS A520.6(b) distinguishes SAPs from other analytical procedures. It also clarifies that SAPs are designed to detect material misstatements at the assertion level and must:
- be based on auditor’s expectation that is sufficiently precise to identify differences that may indicate a material misstatement; and
- use plausible and predictable relationships among financial information, non-financial information, or both.
Why it matters
- Enhances clarity and consistent practice by establishing clearer features that differentiate SAP from analytical procedure used in other aspects of the audit.
- Changes respond to practical challenges about procedures sometimes being labelled as SAP when they are too high level, generic, insufficiently disaggregated, or imprecise to detect a material misstatement.
Relevant sections
ED-ISA 520
- Explanatory Memorandum – Section 1–B, paragraphs 10-13.
- Proposed paragraphs ISA 520.6(b), 8(b), and A8-A20.
Overall ED
- Explanatory Memorandum – Section 1-A, paragraph 40.
Results of analytical procedures performed as risk assessment procedures
Key proposed changes
- Proposed refining the extant definition of “analytical procedures” to remove the sentence that refers to investigating identified fluctuations or relationships. This is because an investigation is a potential follow up response rather than a defining characteristic.
- Proposed paragraph ISA 520.7 clarifies how unexpected results are addressed when performing analytical procedures as risk assessment procedures.
Why it matters
- Proposed definition of “analytical procedures” appropriately focuses on the characteristics of analytical procedures rather than including what the auditor is required to do with them.
- Proposed paragraph ISA 520.7:
- supports the increased use of analytical procedures in risk assessment, such as when using technological tools to analyze larger volumes of information, including entire populations of transactions.
- considers the effect of unexpected or inconsistent results from analytical procedures, reinforcing the iterative nature of risk identification and assessment, which may identify new or revised risks.
Relevant sections
ED-ISA 520
- Explanatory Memorandum – Section 1–B, paragraph 8 and Section 1-D, paragraphs, 23-24.
- Proposed paragraphs ISA 520.1(a), 2, 5(a), 6(a), 7, and A6-A7.
Overall ED
- Explanatory Memorandum – Section 1-A, paragraph 39.
Designing and performing SAPs
Key proposed changes
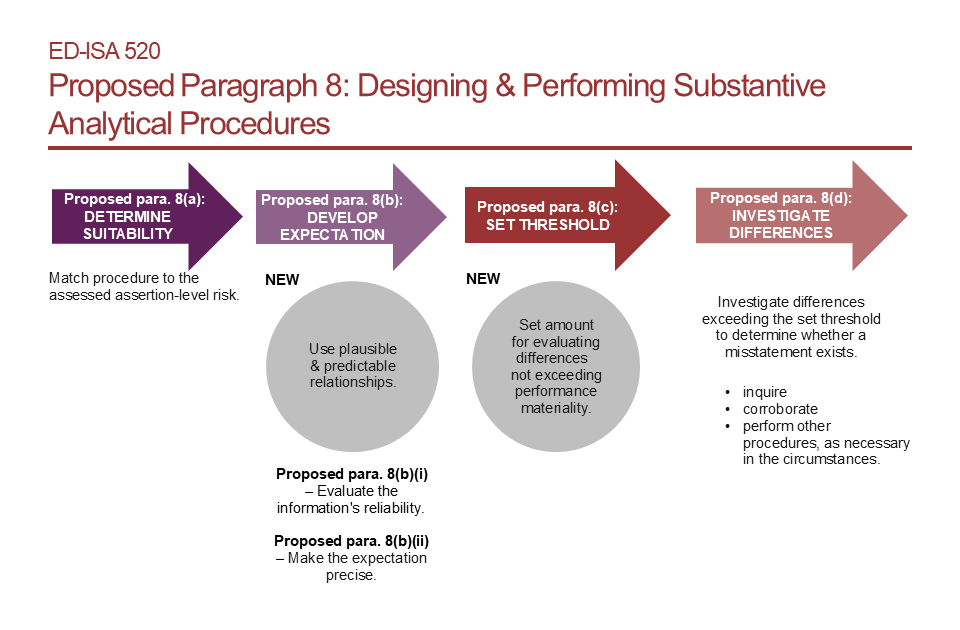
- Enhancements to the requirement for designing and performing SAPs:
- In developing the auditor’s expectation, the lead-in sentence of the requirement in paragraph ISA 520.8(b) emphasizes that the auditor’s expectation is based on one or more “plausible and predictable relationships” among information.
- The proposed requirement in paragraph ISA 520. 8(c) explicitly requires that the threshold to evaluate differences from expected amounts that are acceptable without investigation does not exceed performance materiality.
See PDF below for an overview of proposed paragraph ISA 520.8.
Why it matters
- Strengthens the precision of an SAP by:
- highlighting that the auditor’s expectation is based on plausible and predictable relationships; and
- requiring the auditor to set a threshold for evaluating differences from expected amounts that does not exceed performance materiality. If the threshold is too high, the SAP is unlikely to be effective in detecting material misstatements at the assertion level.
Relevant sections
ED-ISA 520
- Explanatory Memorandum – Section 1-C, paragraphs 14-22.
- Proposed paragraphs ISA 520.8(b)-(d) and A12-A24.