Land Acknowledgement
We, the Canadian Auditing and Assurance Standards Board (AASB), acknowledge that the land on which we work and gather is the traditional and unceded territories from coast to coast to coast of First Nation, Métis, and Inuit (“Indigenous”) Peoples, who have stewarded this land for generations.
We recognize and respect the significance of both treaty and unceded lands, and we are committed to recognizing the diverse history and culture of Indigenous Peoples across Canada in our work. Advancing reconciliation is fundamental to standard setting in Canada, and we are deepening our commitment through meaningful action, which for the current year includes:
- Continuing to strengthen our relationships with Indigenous Peoples and their communities, to enhance the inclusion of Indigenous perspectives in our standard-setting processes.
- Progressing our project to consider Indigenous matters in our sustainability assurance standard.
We recognize that reconciliation requires continuous dialogue, collaboration, and action, and we are dedicated to fostering an approach to our work that is inclusive, representative, and responsive to Indigenous voices. These efforts are one step in our ongoing commitment to advance reconciliation within standard setting and to ensure that our standards meaningfully reflect Indigenous perspectives.
Our Purpose
We operate as independent decision makers with the authority and responsibility to set standards for quality management, audit, sustainability assurance, other assurance, and related services engagements in Canada.
Our Mission
We serve the public interest by setting high-quality standards and supporting their effective application to address the evolving needs of interested and affected parties in Canada.
Serving the Public Interest
The public interest is an overriding consideration for all the AASB activities.
To guide the development of this Annual Plan, we monitor the environment and engage regularly with interested and affected parties. We serve a number of interested and affected parties, including:
- members of the public;
- users of externally reported information;
- those charged with governance;
- governments (federal, Indigenous, provincial, and municipal);
- regulators;
- preparers;
- practitioners, including:
- professional accountants, both from larger firms and smaller firms, and
- other professionals performing assurance engagements;
- other Canadian, national, and international standard setters; and
- other interested parties.
Our Strategy
The 2026-2029 Strategic Plan outlines our five strategic goals and how we plan to fulfill them. Our goals reflect our environment and have been developed to direct our annual plans for fiscal years 2026 to 2029.
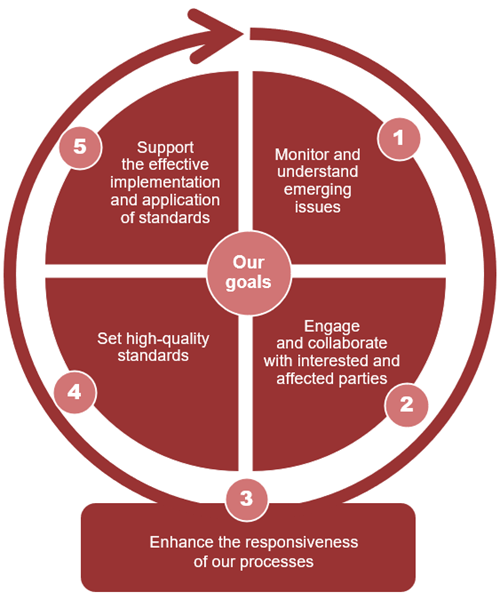
Our 2026-2027 Annual Plan is effective from April 1, 2026, to March 31, 2027. This will be the second annual plan under our 2026-2029 Strategic Plan.
Back to top
Goal 1: Monitor and understand emerging issues in the changing environment to better anticipate their impact on our standards and standard-setting activities
| Activities |
|
Monitor current trends and the evolving needs of interested and affected parties through the AASB’s emerging issues monitoring process. On a semi-annual basis, review the potential impact on standards. This will include considering:
- inspection findings from the Canadian Public Accountability Board (CPAB) and the provincial Chartered Professional Accountant (CPA) bodies;
- financial reporting in emerging industries, evolving uses of technology, and changing business practices;
- sustainability and other external reporting and assurance beyond the financial statements; and
- the needs of interested and affected parties for new or different services.
Conduct targeted outreach activities to better understand key emerging assurance services as they evolve, including whether there is a gap in standards, who it impacts, and how best to respond.
|
Back to top
Goal 2: Engage and collaborate with interested and affected parties to understand their needs and expectations
| Activities |
|
On an ongoing basis, seek input from interested and affected parties, and review semi-annually the impact on standards. This may include specific outreach activities with different groups, such as:
- audit, securities, and prudential regulators including CPAB, Canadian Securities Administrators, and the Office of the Superintendent of Financial Institutions;
- CPA Canada and provincial CPA bodies;
- legislative auditors, including the Canadian Council of Legislative Auditors;
- practitioners who audit large and/or listed entities; and
- practitioners who audit less complex entities (LCEs).
Complete an engagement process analysis on relevant projects at key due process stages to:
- identify the interested and affected parties;
- develop a tailored outreach strategy; and
- evaluate the outcome of the outreach strategy and whether sufficient engagement was achieved.
Seek input from interested and affected parties on:
- All documents for comment the AASB expects to issue, including:
- *Audit Evidence and Risk Response exposure draft; and
- *Targeted Standards in Canadian Auditing Standard (CAS) 500 Series exposure draft.
- Other relevant International Auditing and Assurance Standards Board (IAASB) consultations, including:
- *Post-implementation review of International Standard on Auditing (ISA) 540, Auditing Accounting Estimates and Related Disclosures; and
- *Draft IAASB Strategy and Work Plan for 2028-2031.
Leverage feedback on international projects to inform our responses to the IAASB on its documents for comment and other consultations by the comment deadline.
|
*IAASB document for comment
Back to top
Goal 3: Enhance the responsiveness of our standard-setting processes
| Activities |
- Provide ongoing support to the Canadian IAASB member through an AASB Staff Technical Advisor.
- Provide input on the development of the IAASB’s strategy and work plan for 2028-2031.
- Actively participate as a jurisdictional standard setter (JSS) contributor to the IAASB’s Technology Advisory Network and its planned ongoing monitoring activities.
- Monitor changes to the IAASB’s governance and operations under their staff-led model and identify opportunities to enhance the AASB’s processes and influence.
- Identify and leverage opportunities for learning and collaboration with key parties in the assurance ecosystem, including other Canadian standard-setting boards, provincial bodies, and regulators.
- Review and update, if necessary, the AASB’s Terms of Reference, Statement of Operating Procedures, and Standard-setting Due Process Manual.
|
Back to top
Goal 4: Set high-quality standards that respond to the needs and expectations of interested and affected parties
| Activities |
- Monitor and provide Canadian perspectives on all IAASB projects, including whether proposed revisions in current ISA projects effectively deal with scalability and proportionality for audits of LCEs.
- *Audit Evidence and Risk Response
- Sustainability Assurance
- Approve Canadian amendments to reflect the consideration of Indigenous matters in the Canadian Standard on Sustainability Assurance 5000, General Requirement for Sustainability Assurance Engagements.
- *Targeted Standards in CAS 500 Series
- *Technology Quality Management Workstream
- Involve technology subject-matter experts in review of draft non-authoritative materials.
- Provide targeted input on the first revision of the IAASB’s ISA for LCE, when relevant to the needs and interests of Canadian interested and affected parties and development of a Canadian solution.
- Consider whether Section 7060, Auditor Review of Interim Financial Statements, remains fit for purpose in light of the IAASB's project on International Standard on Review Engagements 2410, Review of Interim Financial Information Performed by the Independent Auditor of the Entity.
- Participate in discussions with other JSSs to strengthen relationships and international influence, as well as identify opportunities for collaboration. This includes:
- meeting regularly with other JSSs; and
- participating in IAASB JSS meetings.
|
*IAASB projects
Back to top
Goal 5: Support the effective implementation and application of standards to enhance consistency and quality in engagement performance
| Activities |
- Complete an implementation risk analysis on all standard-setting projects. This analysis includes considering the nature of potential implementation challenges at the final approval stage.
- Monitor and assist in the development of implementation guidance and other guidance by others, including other JSSs. Topics may include:
- compilation engagements of future-oriented financial information and pro forma;
- going concern;
- fraud;
- technology; and
- sustainability.
- Conduct targeted outreach to better understand application challenges with recently implemented CAS 315, Identifying and Assessing the Risks of Material Misstatement and Canadian Standard on Related Services 4200, Compilation Engagements.
- Determine how best to respond to feedback and undertake necessary actions. These actions may include developing guidance in partnership with others.
- Monitor changes in securities legislation and consider whether standards remain fit for purpose or whether guidance is needed.
- Using the Audits of LCE Working Group, facilitate timely and impactful actions to support the efficient and effective application of the CASs to audits of LCEs.
- Monitor and provide Canadian perspectives on all IAASB post-implementation reviews, including where there are challenges with the scalability and proportionality of the standards for audits of LCEs.
|
Back to top
Risks and Accountability
Effective risk management is central to fulfilling our mandate. We identify pervasive risks, implement mitigating activities, and monitor environmental developments to ensure we remain aligned with our mission.
We report annually to the Reporting & Assurance Standards Oversight Council on our performance. We measure achievement of our strategies by:
- setting out the specific activities to support the achievement of our strategies in our annual plans; and
- measuring and reporting on our performance based on our annual activities and our strategic goals.
Back to top